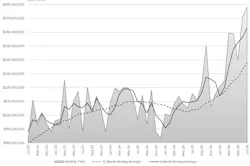
U.S. machine shops and other manufacturers ordered $278.1 million worth of cutting tools during July 2026, 2.8% more than the total for June shipments and 29% more than the total for July 2025. These results are reported in the latest Cutting Tool Market Report compiled jointly by AMT - the Assn. for Manufacturing Technology and the U.S. Cutting Tool Institute.
As cutting tools are “the primary consumable” used by manufacturers across multiple manufacturing sectors - automotive, aerospace, construction, defense, energy, and other industrial products - the current results confirm the steady growth of U.S. manufacturing activity. According to the current CTMR, year-to-date cutting tool shipments totaled $1.75 billion, up 20.7% from January-July 2025.
However, the current rise in shipment values also indicates that inflation is affecting cutting tool demand, as unit shipments remained steady from June to July.
Inflation has also been detected as a factor driving U.S. machine tool orders - though inflation’s effect on the market varies according to its cause(s): in the monthly Purchasing Managers Index of industrial consumption, inflation affects input prices, output prices, new orders, and suppliers' delivery times, and its overall effect depends on whether the inflation is mainly driven by buyers’ demand or the supply/cost of the particular product.
“Consumption (of cutting tools) continues at a high level as most shops work on their backlog and incoming orders,” observed BIG Daishowa president Jack Burley, chairman of AMT’s Cutting Tool Product Group. “The carbide crisis has, however, increased user costs by double digits, most notably for the larger tools. Given the increased demand and higher costs, July saw the highest monthly total ever, beating the previous record set in June 2026. And until the market cools down, this trend will continue for the remainder of 2026 and into 2027.”
Burley refers to extreme market volatility, price spikes, and supply chain bottlenecks surrounding tungsten carbide, which is the primary alloy used in manufacturing high-performance CNC cutting tools like end mills, drills, inserts, and reamers. Tungsten carbide combines exceptional hardness, heat resistance, and wear resistance required in most machining operations.
However, the supply of raw materials for tungsten carbide alloy dominated by Chinese sources.
The “crisis” became more acute in recent months, with price surges in raw material costs. The U.S. has set a January 1, 2027 deadline for defense contractors sourcing tungsten metal powder and heavy alloys sourced from restricted nations (e.g., China, North Korea, Russia, and Iran.)
“Cutting tool shipment growth is robust – but it is occurring amid an inflationary environment,” according to Michelle Kocses, an ITR Economics senior economist quoted by CTMR. “Growth in the manufacturing sector supports demand, but that growth is unevenly distributed. Legacy markets, such as automotive, are stagnant, while the high-tech and defense industries are booming.
Kocses continued: “The inventory cycle in the durable goods space is likely to wind down in 2027, and consumer markets will be muted by weak real incomes and elevated borrowing costs.”
About the Author
Robert Brooks
Content Director
Robert Brooks has been a business-to-business reporter, writer, editor, and columnist for more than 20 years, specializing in the primary metal and basic manufacturing industries.